August 20, 2026
Buy Now Pay Later Refunds in 2026: Your Rights Compared
The Xbox got more expensive this month. The financing offer sitting next to it at checkout did not. That pairing is the whole story of consumer electronics this year: the hardware costs more, and the company selling it would very much like you to spread the damage across a few instalments instead of walking away.
Instalment plans at the point of sale used to be a fringe option for clothing. Now they are a default button on consoles, laptops, phones and televisions. And the protection attached to that button is not what most buyers assume it is.
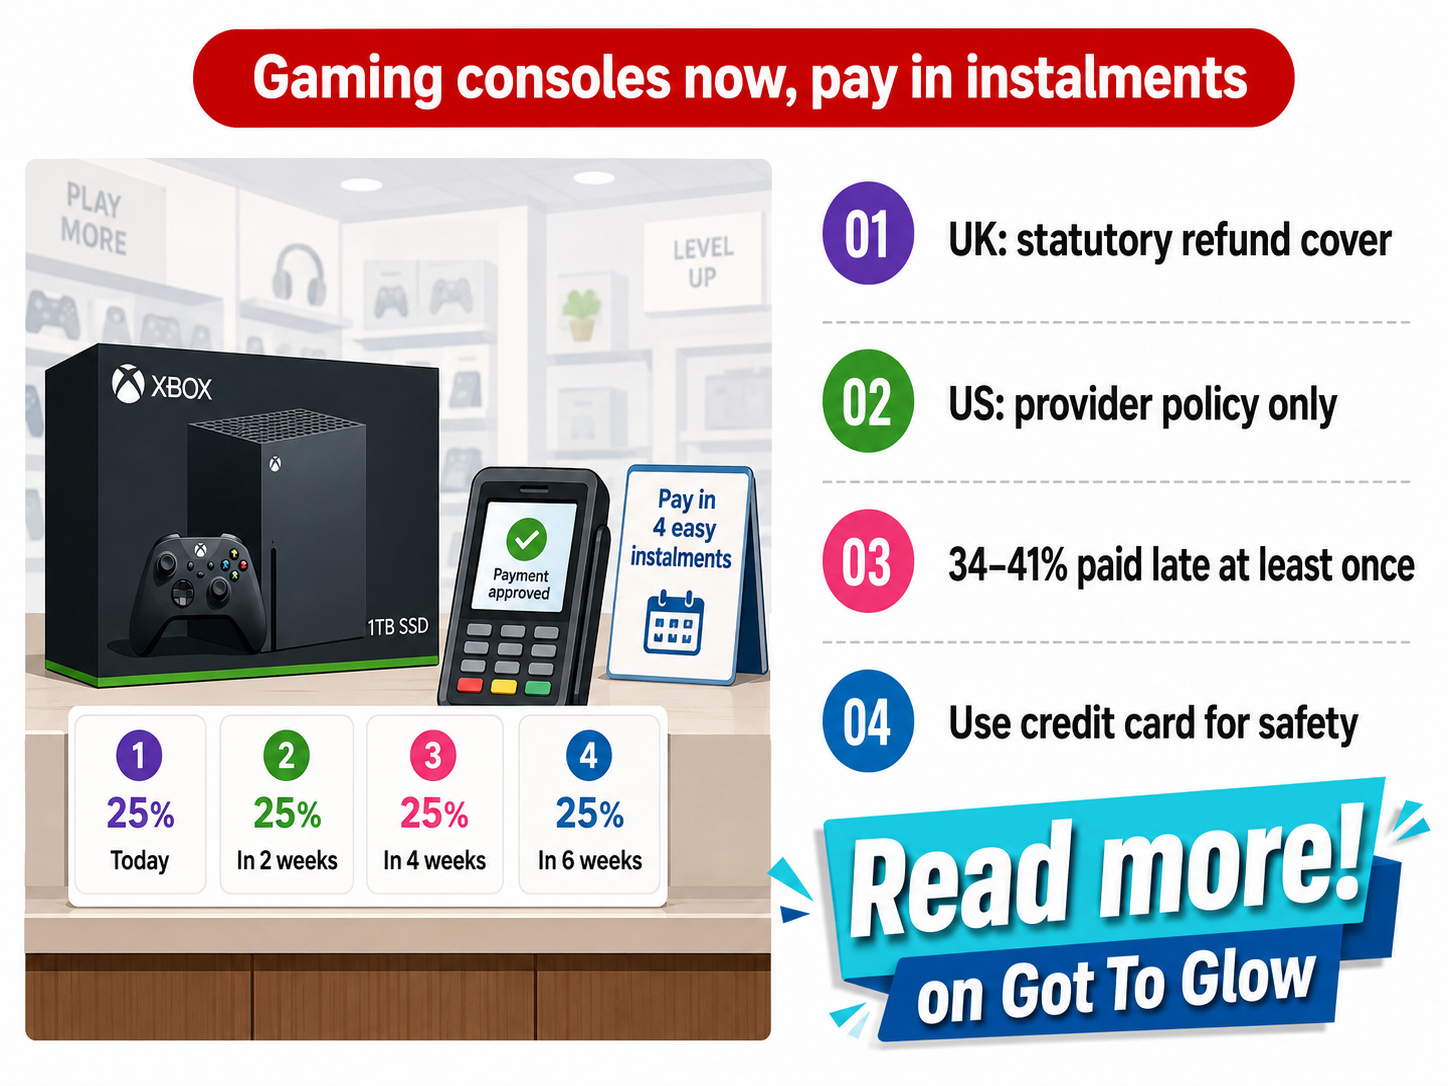
TL;DR: Component costs are pushing device prices up, and vendors are answering with instalment plans at checkout. What that plan protects depends entirely on where you live: statutory refund cover on new UK agreements, and nothing more than provider policy in the US.
Why It Matters
Start with the price pressure, because it explains the timing. Microsoft announced on 25 June 2026 that the 512GB Xbox would rise by $100 from 1 August, its second increase in under a year, and said storage and memory costs had gone up two and a half times over. In the same announcement it offered Buy Now Pay Later, interest-free financing and cheaper refurbished units. That is a company reading its own demand curve correctly. Fewer people can absorb the new sticker price, so the sticker price gets broken into pieces.
Breaking a price into pieces is not automatically a bad deal. Four payments at zero interest beats a credit card balance you carry for eight months, and for a lot of households it is the difference between replacing a dead laptop now and going without. The problem is what quietly changes when you press that button instead of the card one. You are no longer making a card purchase with decades of dispute law wrapped around it. You are taking out a small loan from a company whose refund policy is, in most markets, its own invention. This is the same structural gap that shows up when software starts spending on your behalf, which is why who pays when an AI shopping agent buys the wrong thing is still an open question.
The rules moved after the meter did, the same sequence that played out when usage-based AI billing reshaped the software budget. Two things happened five weeks apart that pulled the two biggest English-speaking markets in opposite directions. In the UK, the Financial Conduct Authority began regulating Deferred Payment Credit in mid-July 2026, which brings affordability checks, Section 75 refund cover through the lender, and access to the Financial Ombudsman Service. Agreements signed before that date stay unregulated, so the plan you took out in June carries none of it. In the US, the Consumer Financial Protection Bureau revoked the interpretive rule that would have treated these plans like credit cards for dispute purposes, and confirmed it would not issue a replacement. Same product, same app, opposite floors.
Typical pay-in-four window
6 weeks
Four payments, fortnightly
Xbox 1TB price rise
$150
Microsoft, effective August 2026
Global BNPL volume, 2025
$560.1B
Fortune Business Insights estimate
Users late at least once
34% to 41%
CFPB borrower study, 2025
The late-payment figure is the one worth sitting with, because it is not describing people in financial trouble. Default rates stay low. What it describes is a repayment schedule that does not line up with how anyone actually gets paid, running quietly in the background while three other schedules do the same thing. Miss one and the cost is a flat fee rather than interest, which sounds gentler and often is not, because a fixed fee on a small balance is a brutal effective rate.
A $150 jump on one console is not a pricing footnote. It is the reason the instalment button moved from the clothing checkout to the electronics aisle.
What Each Payment Method Actually Protects
Below is the comparison nobody selling you a plan is going to put on screen. It covers the three ways most people pay for a device that costs real money, judged on what happens when the thing arrives broken, never arrives, or turns out to be nothing like the listing.
| Dimension | Pay-in-four plan | Credit card | Debit card |
|---|---|---|---|
| Dispute route | The provider's own resolution flow, on its timetable | Issuer billing dispute, with the card network behind it | Bank chargeback request, scheme rules only |
| UK cover | Section 75 through the lender, on newly regulated agreements only | Section 75 on purchases above £100 and up to £30,000 | No statutory cover, voluntary chargeback only |
| US cover | Nothing guaranteed, provider policy decides | Billing-error rights, claim within 60 days of the statement | Unauthorised-transaction cover, weak on quality disputes |
| Cost on time | Usually nothing on a short pay-in-four plan | Nothing if the statement clears in full | Nothing, the money simply leaves |
| Cost if you slip | Flat late fee, harsh against a small balance | Interest on the carried balance plus a late fee | Overdraft charges from your own bank |
| Credit file | Patchy, some providers report short plans and some do not | Always reported, good months and bad | Never reported, builds nothing |
| Escalation | Ombudsman in the UK, goodwill in the US | Ombudsman or regulator in both markets | Your bank's complaints process, then the regulator |
| Fits which purchase | Small to mid, split across a handful of instalments | Anything inside your limit, including big-ticket | Only what is already in the account |
| Best Suited For | Cash-flow smoothing on a purchase you already trust | Anything expensive, remote, or from an unfamiliar seller | Small, low-risk buys from a shop you can walk back into |
Read down the dispute-route row and the pattern is obvious. The instalment plan is the only column where the company you are complaining about and the company deciding your complaint answer to the same commercial pressure. That is not fraud. It is just a worse seat at the table, and it costs nothing at the moment of purchase, which is exactly why it is easy to miss.
Two reporting changes and one regulator arrived in that order, which is why a plan taken out in 2024 and an identical plan taken out today can behave completely differently on your credit file and in a refund fight.
Friction Points
The credit-file question is where honest people disagree, and I am not going to pretend it is settled. Putting short instalment plans into credit files could finally give thin-file borrowers a way to prove they repay things, which is the industry's argument and a decent one. It could equally turn a forgotten $40 payment into a score event that follows someone for years, on a product marketed as too small to matter. Both futures are plausible right now, and anyone claiming certainty is selling something.
The second friction is a design problem, not a policy one. These plans are approved in seconds, at the moment your resistance to spending is lowest, on a screen that shows the instalment and not the total. Stack three of them across three retailers and no single provider sees the whole picture. That is a familiar shape if you have ever compared subscription tiers and found the real cost buried two clicks deep, the way the family sharing fine print in Google One and OneDrive hides who is actually paying for what.
Watch for these specifically:
- The pre-regulation gap. A UK plan opened before the new rules took effect is not covered by them. Check the agreement date before assuming Section 75 applies.
- Refunds that go to the wrong place. Money can be returned to the provider while your instalments keep running. Confirm the plan is cancelled, not just that a refund was approved.
- The unfamiliar-seller trap. Instalment plans are heavily promoted on low-cost gear, which is precisely where quality disputes cluster, and where cheap televisions from brands you have never heard of tend to go wrong.
- Late fees that outrun interest. On a small balance, one flat fee can beat a month of card interest. Do that arithmetic before choosing.
Key takeaways worth keeping
- A joint FICO and Affirm study of roughly 500,000 borrowers found score movement within plus or minus 10 points for more than 85% of the consumers examined, so the reporting shift is real but not seismic.
- IDC's memory-shortage scenarios put average PC selling prices up 4% to 6% this year, and 6% to 8% if the shortage runs long, which keeps the financing pitch in front of you.
- US buyers should treat instalment refund policy as a product feature to compare, not a legal guarantee, because no federal rule currently supplies one.
Pick the payment method by what could go wrong, not by what the checkout screen nudges you toward. Expensive item, unfamiliar seller, shipped rather than carried home: use the card, take the dispute rights, clear it in full. Everything else is a cash-flow decision you can make on the merits. Before the next big purchase, open your instalment app and count how many plans are already running. That number is the answer to a question most people never ask themselves.
Related: what the new EU legal guarantee notice gets you from 27 September 2026
Related: chargeback rights when a seller refuses to refund a faulty gadget